
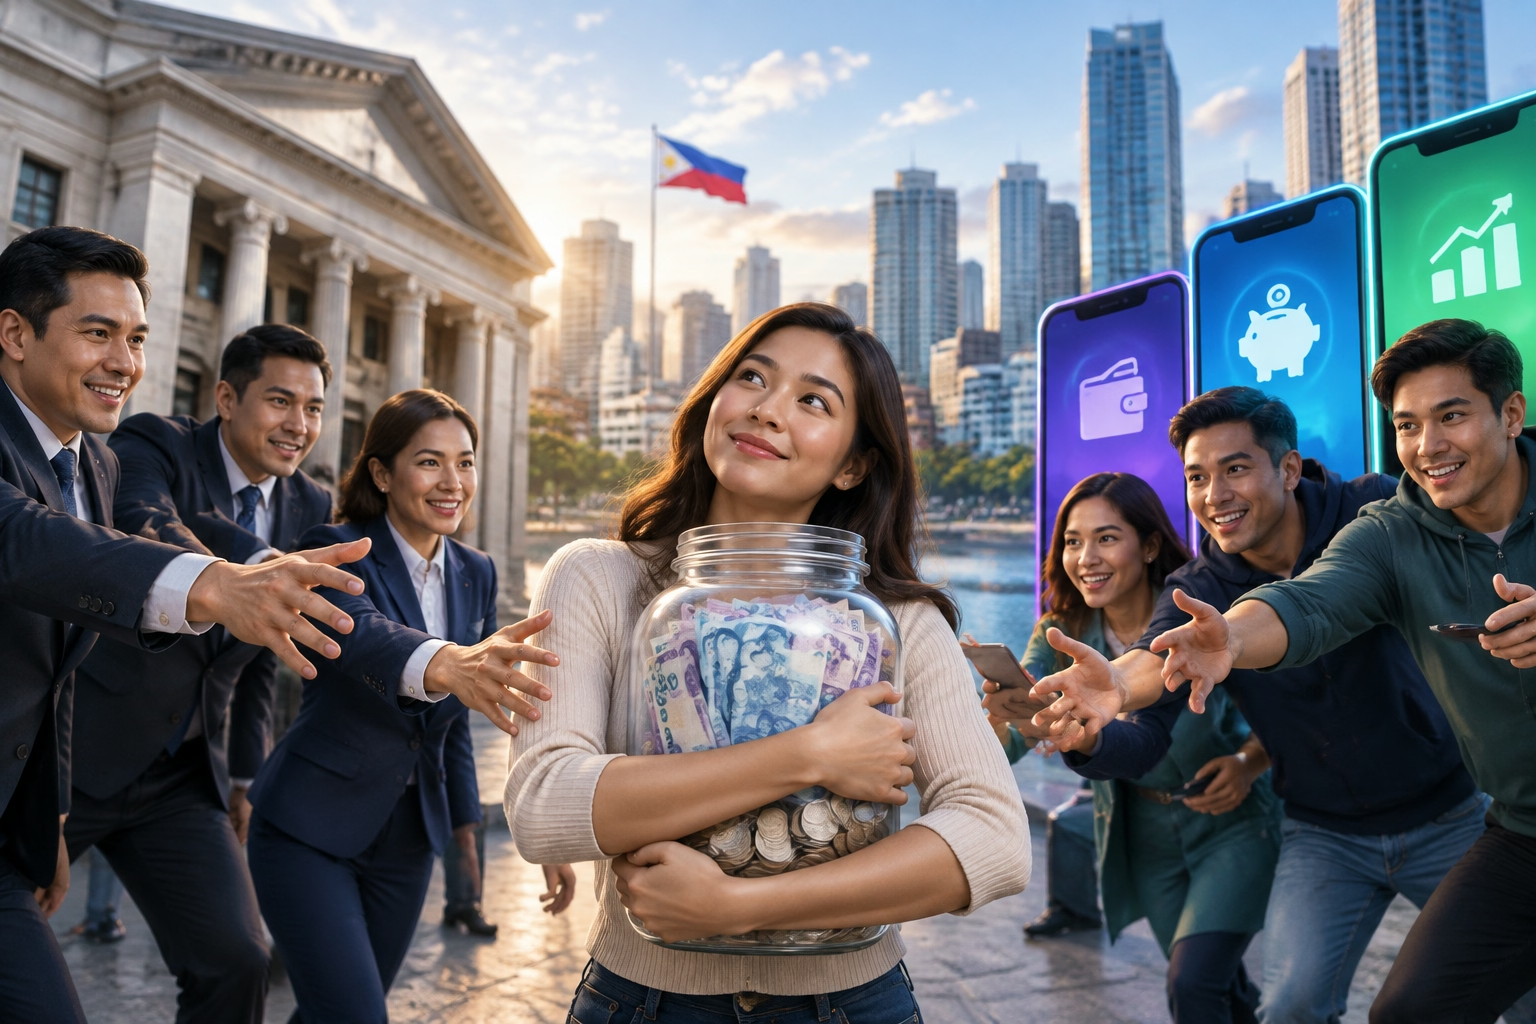
The Philippine banking landscape has transformed into a high-stakes battlefield. For decades, Filipino savers were accustomed to meager interest returns on their deposits, often hovering below 1%. However, the financial paradigm has shifted dramatically. As we navigate through 2026, the competition for liquidity among the country’s largest financial institutions has intensified, creating a fertile ground for depositors seeking better returns.
This isn’t just about a slight bump in percentage points; it is a strategic war for the massive pool of household savings. Banks are no longer passive recipients of cash; they are actively courting funds to fuel their lending operations and meet regulatory requirements.
The Macroeconomic Backdrop
The primary driver of this intense competition is the monetary policy stance of the Bangko Sentral ng Pilipinas (BSP). Following a period of aggressive rate hikes to combat inflation, the BSP has maintained a relatively tight policy stance to ensure price stability. According to recent data from the Bangko Sentral ng Pilipinas (BSP), the policy rate remains a critical benchmark that dictates the floor for time deposit rates.
When the central bank adjusts rates, commercial banks are forced to recalibrate their own offerings. In early 2026, we observed that universal banks began aggressively matching the yields offered by digital banks to prevent capital flight. This phenomenon is known as “deposit disintermediation,” where funds move from low-yield traditional banks to high-yield digital alternatives.
Digital Disruptors vs. Traditional Giants
The entry of digital banks (such as Maya Bank, GoTyme, and SeaBank) served as the catalyst for this revolution. These digital-first institutions, unburdened by the overhead costs of maintaining thousands of physical branches, passed those savings onto consumers in the form of high interest rates—sometimes reaching as high as 6% to 7.5% per annum on savings accounts.
Traditional banking giants like BDO Unibank, Bank of the Philippine Islands (BPI), and Metrobank initially resisted the urge to engage in a rate war. However, as digital banks gained significant market share, the “Big Three” have been forced to innovate. We are now seeing a tiered interest rate structure where traditional banks offer competitive rates for “premium” or “relationship” balances, aiming to lock in high-net-worth individuals.
Implications for the Filipino Saver
For the average Filipino, this competition is a boon. The era of “parking” money in a passbook account with zero growth is over.
- Higher Yields: Savers can now earn real returns (interest minus inflation) if they choose the right institution.
- Product Innovation: Banks are introducing features like “Goals” based savings buckets that offer higher rates for specific purposes.
- Financial Literacy: The competition has forced banks to educate consumers on the difference between simple and compound interest.
The Liquidity Crunch
Despite the high rates, banks are facing a liquidity crunch. As the economy accelerates, demand for business loans and consumer credit is rising. Banks need deposits to fund these loans. Without a strong deposit base, banks cannot lend, and without lending, they cannot profit from the interest rate spread.
Consequently, we are seeing aggressive marketing campaigns not just on social media, but through traditional channels. Referral programs, cash incentives for payroll accounts, and waived fees are becoming standard operating procedures. The battle for the Filipino peso is no longer fought in marble lobbies, but in the digital wallets and apps of millions of Filipinos.
As 2026 progresses, experts predict that rates will stabilize but remain significantly higher than pre-pandemic levels. The structural change in how banks view depositors—from mere storage to active partners—is likely here to stay.


Leave a Reply